Training in Machine Learning for Quantitative Finance

ARPM builds advanced statistical competence to work in modern financial engineering, risk management and quantitative investment

CAREER PATHWAYS THROUGH ARPM CERTIFICATION

Build skills for your next step in quantitative finance

Develop the mathematical, statistical, data science, and machine learning skills required to tackle complex financial problems. Connect your learning to three professional areas.

Financial Engineering

Build real-probabilty analytics platforms

Learn to price instruments across asset classes, model market dynamics, and estimate future payoffs using mathematical, statistical, and machine learning methods.

Relevant roles

Risk/Portfolio Analytics Engineer

Quantitative Risk Management

Leverage statistics to prevent losses

Learn to measure risk, analyze stressed scenarios, and use statistical and machine learning models to identify the drivers of risk exposure.

Relevant roles

Quantitative Risk Manager

Quantitative Investing

Build portfolios with science

Learn to extract investment signals, construct portfolios, optimize trade execution, and evaluate performance using statistical and machine learning techniques.

Relevant roles

Quantitative Portfolio Manager Portfolio Construction Engineer Systematic Investment Researcher

One integrated framework connects all three areas—from modeling financial instruments and managing risk to generating investment signals and implementing portfolio decisions.

How you will Learn

One advanced curriculum, delivered through three complementary learning formats.


Why ARPM?

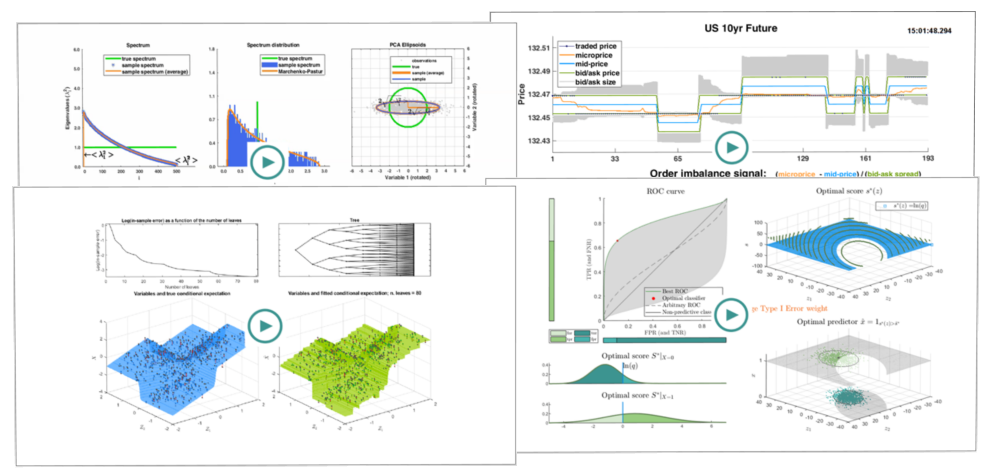
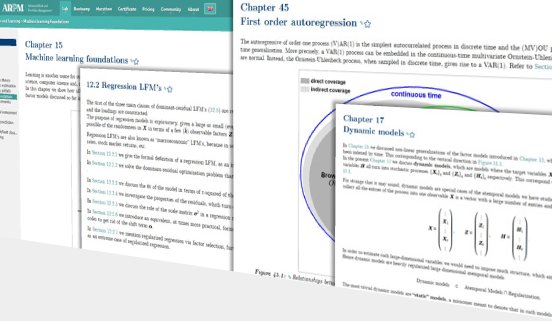
Only ARPM has the Lab, a 3,500-page e-textbook on machine learning and its applications across all of quantitative finance, with code, animations, and an AI tutor, learn more about the Lab.

  1. No gaps, no overlaps. Most programs are taught on a collection of scattered references, with conflicting notation, overlapping topics and gaps. The Lab is written in succinct, unified, mathematical language and constantly updated for inclusiveness and consistency.
  2. Principles first. Innovation in AI is chaotic and relentless: to remain competitive you need to understand the core principles behind any new techniques. The Lab is structured around:
    • The “Machine Learning Ecosystem” – a framework for organizing all of Machine Learning from the simplest principles to the most advanced innovations, learn more about Machine Learning.
    • The “10-Step Checklist of Finance” – a framework for organizing the entire fields of Financial Engineering, Risk Management and Quantitative Investment, learn more about Quantitative Finance.

ARPM by the numbers

5,000+

Alumni

Quant Bootcamp-ers and Certification holders, since 2009

100,000+

Lab code lines

All case studies and examples implemented on Jupyter Lab, no installation required

3,500+

Lab pages

Overarching notation across Machine Learning and Quantitative Finance


Testimonials

Leif Andersen

Global Co-Head of Quantitative Analytics, Bank of America

Boris Deychman

Head of Model Risk Management, DTCC

Mike Sternberg

Global Head Of Aladdin Financial Engineering, BlackRock

These professionals chose ARPM for team upskilling. While company policy restricts official endorsements, they are happy to provide personal references upon request. All views expressed are their own and do not necessarily reflect those of their employers.