ARPM Professional Certification

Advance Your Quant Career

Certification in Machine Learning for Quantitative Finance

ARPM Certification and a Statement of Completion for each course included

$11,500$7,750Limited-time price
30%+ OFF
Enroll now (opens in a new tab) Contact us

Career

Accelerate Your Quant Career

Build the machine learning and quantitative finance foundations to move from a technical background into advanced quantitative roles.

Mathematical background Advanced ML toolkit Quant professional
Background

Investment Analyst

Target role

Quant Researcher / Quant Portfolio Manager
Background

Software Engineer

Target role

ML Engineer for Finance

Background

Risk Associate

Target role

Quant Risk Manager

Background

Data Analyst

Target role

Financial Data Scientist


Program

A Comprehensive 10-Month Learning Journey

One progression connects mathematical foundations, modern machine learning, and financial decisions across two specialized tracks.

Courses in track “Machine Learning”

The courses in this track cover in depth the Machine Learning topics in the Lab, learn moreabout the Machine Learning track .

Mathematical Statistics for Finance

Mathematical Statistics for Finance

Mathematical Statistics for Finance provides an in-depth discussion of the mathematical topics which lie at foundation of the applications of statistics to finance:

  • The roots of the symmetry between the Mean-Covariance versus the Probabilistic Framework;
  • The theory to learn from data in both frameworks.

More precisely Mathematical Statistics for Finance consists of the following parts of the "Data Science Map":

  • The Probabilistic Framework describes the essential tools to operate in the Probabilistic Ecosystem, where:
    1. Statistical relationships among variables are modeled by probability distributions;
    2. Transformations among variables are non-linear;
    3. Structure is imposed via independence or more generally via conditional independence, which follows from the notion of conditioning.
    This part also covers copulas and respective implementations.
  • The Mean-Covariance Framework describes the essential tools to operate in the Mean-Covariance Ecosystem, where:
    1. Statistical relationships among variables are modeled by their mean-covariance equivalence classes;
    2. Transformations among variables are linear or affine;
    3. Structure is imposed via uncorrelation, or more generally partial uncorrelation, which follows from the notion of L² linear projection.
    This part also covers measures of dependence and concordance.
  • Decision theory under risk addresses modeling and optimization of decisions under the assumption that the joint mean-covariance classes, or probabilistic distributions, of all random variables are known.
  • Estimation leverages decision theory under uncertainty to learn, from data, relevant features of the joint mean-covariance classes, or probabilistic distributions, when these are not known. Key concepts include elicitability, asymptotic/random matrix theory, hypothesis testing.
  • Inference covers how to learn not only from data, but also from subjective opinions, both mean-covariance classes (Black-Litterman) and probability distributions (minimum relative entropy).

Mean-Covariance Learning

Mean-Covariance Learning

Mean-Covariance Learning represents the linear blueprint for Probabilistic Machine Learning.

It covers practical ways of learning observational and causal models from i.i.d. data samples and taking optimal decisions within the Mean-Covariance Framework.

The key ingredients are linear factor models, which model all mean-covariance structures: supervised (linear regression); unsupervised (principal component and factor analysis); hybrid (canonical correlation, total least squares); and causal (structural equation models).

This part also covers the estimation of linear factor models, namely mean/loadings and (high-dimensional) covariance matrices, in the context of financial applications.

This part covers the below portion of the "Data Science Map".

Probabilistic Machine Learning

Probabilistic Machine Learning

Probabilistic Machine Learning discusses machine learning/artificial intelligence models, presented as generalizations of Mean-Covariance Learning.

It covers practical ways of learning observational and causal models from i.i.d. data samples and taking optimal decisions within the Probabilistic Framework.

The key ingredients are conditional distributions, which model all probabilistic structures: supervised learning (point and probabilistic); unsupervised learning (autoencoders and graphical models); and one-period reinforcement learning (causal Bayesian networks).

This part also covers the estimation of specific conditional distributions in the context of financial applications.

This part covers the below portion of the "Data Science Map".

Time Series and Reinforcement Learning

Time Series and Reinforcement Learning

Time Series and Reinforcement Learning covers the dynamic counterparts of Mean-Covariance Learning and Probabilistic Machine Learning.

It covers practical ways of learning observational and causal models and taking optimal decisions in both the Mean-Covariance Framework and the Probabilistic Framework, when data is not i.i.d.

As such, this part includes multivariate econometrics, continuous time stochastic processes, and optimal sequential decision making.

This part covers the below portion of the "Data Science Map".

Courses in track “Quantitative Finance”

The courses in this track cover in depth the Quantitative Finance topics in the Lab, learn moreabout the Quantitative Finance track .

Financial Engineering

Financial Engineering

Financial Engineering covers Steps 1-4 of the "Checklist".

Step 1 discusses how to price instruments across asset classes by means of the so-called risk-neutral or "Q" measure, as well as variations such as the CAPM or the APT.

Step 2 discusses how to convert raw financial data into well-behaved times series.

Step 3 discusses how to use econometric tools to model and estimate the evolution of such time series in the so-called real world or "P" measure.

Step 4 discusses how to map the future evolution of the time series back into the object of interest, which is joint distribution of the instruments future payoff.

This part covers the below portion of the "Quantitative Finance Checklist".

Portfolio and Enterprise Risk Management

Portfolio and Enterprise Risk Management

Portfolio and Enterprise Risk Management covers Steps 5-7 of the "Checklist":

Step 5 discusses how to compute the aggregate value of a given portfolio, based on the portfolio's holdings; and how to aggregate the future payoff of each instrument into the future payoff of the portfolio under regular and stress market conditions.

Step 6 discusses how to assess the overall risk in a given portfolio at the fund, desk, or enterprise level.

Step 7 discusses how to attribute the overall risk to the contribution of different factors.

This part covers the below portion of the "Quantitative Finance Checklist".

Portfolio Construction and Trading

Portfolio Construction and Trading

Portfolio Construction and Trading covers Steps 8-10 of the "Checklist".

Step 8 discusses how to construct theoretical static portfolios based on mean-variance optimization or more complex algorithms; and to build dynamic investment strategies based on cross sectional heuristics or option based portfolio insurance.

Step 9 discusses how to implement a theoretical allocation in practice by optimally scheduling small orders in an electronic exchange.

Step 10 discusses how to assess past realized performance and attribute profits and losses to different contributors.

This part covers the below portion of the "Quantitative Finance Checklist".

For participants who want to refresh their knowledge or prepare for a smooth progression through the core courses, each Track also includes Primers, which cover the respective topics in the Lab, learn moreabout the Primers .

The Primers are free of charge, self-paced, and optional.

Mathematics Primer
Finance Primer
Python Primer

7 Advanced Courses

One unified mathematical framework for quantitative finance.

Live & Recorded

Join interactive sessions or learn from high-quality recordings.

Human-Reviewed Work

Expert feedback on practical assignments builds real understanding.

Advisor Support

Guidance from ARPM faculty and specialized advisors.

ARPM Certification and a Statement of Completion for each course included

Enroll Now

ARPM Method

One framework. From statistical foundations to financial decisions.

The Certification integrates Machine Learning and Quantitative Finance through mathematical statistics, financial engineering, portfolio construction, and risk management.

Integrated Framework

Move from statistical inference and estimation to probabilistic machine learning and sequential decisions.

Statistical Foundations

Understand assumptions, estimation methods, uncertainty, and model limitations.

ML & Quant Finance

Apply machine learning to financial data, engineering, portfolio construction, and risk.

Theory to Implementation

Connect mathematical models to numerical implementation through Python and the ARPM Lab.

A professional certification built for applied quantitative finance
Depth of theory

A comprehensive and rigorous theoretical foundation.

Practical code

Python applications integrated throughout the ARPM Lab.

Expert interaction

Live sessions and access to expert guidance.

Support

AI Tutor plus human tutoring support.

Project review

Human review of assignments and projects.

Professional outcome

Certification awarded through individual expert evaluation of a practical project.


Requirements

Program Requirements

These guidelines help you assess your background and choose the preparation you need to benefit fully from the program.

Required

Mathematics

Linear algebra, multivariate calculus, and basic optimization.

Required

Statistics

A solid understanding of probability and statistical inference.

Primer included

Programming

Python experience helps, and the included primer builds the required foundations.

Primer included

Finance

Finance experience helps, and the included primer covers the essentials.

Free Primers Included

Self-paced primers help you refresh and strengthen your foundations before and during the program.

Math Primer
Python Primer
Finance Primer

Have questions about your background or preparation?

Talk to an Advisor

Why ARPM

Built for depth, not shortcuts.

ARPM is built around decades of experience in quantitative investment, risk management, and research.
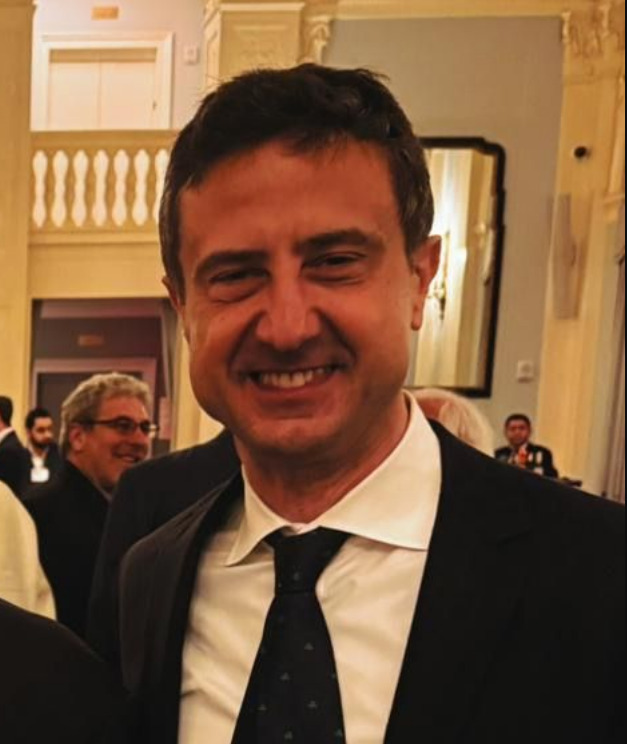
Attilio Meucci

Founded by Attilio Meucci

Attilio Meucci is the founder of ARPM, author of Risk and Asset Allocation, and a former senior quantitative investment and risk practitioner.
Investment leadership
Former CRO at KKR and former CRO & Director of Portfolio Construction at Kepos Capital.
Research and education
Author, journal contributor, and creator of the ARPM Lab.

Professionals from leading institutions have trained with ARPM

Barclays
Invesco US
Amundi
Moore Capital Management
CPP Investments
BlackRock
Abu Dhabi Investment Authority
Bank of America
American International Group
Credit Suisse

What ARPM participants say

Quantitative Research, Portfolio & Risk Management

“A vast wealth of material… quite unified across the program.”

Natasha Gregory

(opens in a new tab)

VP · Risk & Quantitative Analytics

“The strong theoretical material, flexibility, Lab and live classroom sessions really stand out.”

Counterparty Credit Risk

“The two main advantages are the theory materials and the Python code.”

Offer

Limited-Time Offer

$11,500$7,750
30%+ OFF

Ends September 22

Secure enrollment · ARPM Certification included


FAQ

Frequently Asked Questions

Is the Certification in Machine Learning for Quantitative Finance a university degree or a Master’s program?

No. It is a professional certification for professionals and advanced learners who want a rigorous, applied path in machine learning for quantitative finance without enrolling in a university Master’s program.

How is this different from a generic online course or MOOC?

The Certification is built specifically for quantitative finance. It combines mathematical rigor, financial applications, Python implementation, structured learning paths, human-reviewed work, and support from the ARPM learning infrastructure.

Is this suitable if I am comparing CQF, FRM, or other finance certifications?

It depends on your goal. This program focuses on applying machine learning and quantitative methods to real financial problems. It is best suited to professionals seeking practical quantitative finance and machine learning skills.

Is the ARPM Quant Bootcamp the same as the Certification?

No. The Quant Bootcamp is a shorter intensive program. The Certification is a longer, structured program covering both Machine Learning and Quantitative Finance tracks, with a broader curriculum, projects, support, and certification path.

How much mathematics is required?

You should be comfortable with linear algebra, multivariate calculus, and probability. The program is rigorous and quantitative. ARPM Primers can help you refresh these foundations.

How much programming is required?

Python experience is helpful, but you do not need to be a professional software developer. Applied Python work in the ARPM Lab connects theory to implementation and financial applications.

Can I study while working?

Yes. The Certification is designed for working professionals. It is part-time, live classes are recorded, and you can progress alongside a full-time job if you dedicate regular weekly study time.

How long does it take to complete?

The full Certification takes approximately 10 months and is divided into two specialized tracks: Machine Learning and Quantitative Finance.

What support is available?

Participants have access to the ARPM learning platform, AI Tutor support, technical assistance, and human feedback on homework projects.

What happens if I am not sure this is right for my background?

Contact us before enrolling. An advisor can help you understand whether your background, goals, and available study time align with the Certification.


Contact us

A 20-minute conversation with our team is the fastest way to learn whether the ARPM learning methods are the right fit for you, and to get answers about pricing, learning expectations, and more.

Tell us about yourself

How would you like to connect?

ARPM Program Advisor

20 min session