Brian Ertley
 (opens in a new tab)
Quantitative Research, Portfolio & Risk Management
“A vast wealth of material… quite unified across the program.”
Build the machine learning foundations to move from a technical background into quantitative finance.
The Machine Learning Track delivers a unified framework connecting mathematical foundations, modern ML techniques, and real-world financial applications.
SEP · 21/09/26
NOV · 02/11/26
DEC · 14/12/26
FEB · 17/02/27
Built on one unified mathematical framework specifically for quantitative finance.
Join live interactive sessions or learn at your own pace with high-quality recordings.
Practical assignments reviewed with expert feedback to ensure deep understanding.
Direct guidance throughout the journey from ARPM faculty and specialized advisors.
The ARPM Machine Learning Track follows an integrated path connecting mathematical rigor, probabilistic thinking, and real-world financial applications.
From statistical inference and estimation to probabilistic ML and sequential decision-making.
Understand assumptions, estimation methods, uncertainty and model limitations.
Apply the methods throughout to financial data and quantitative-finance problems.
Connect mathematical models to numerical implementation through Python and the ARPM Lab.
The Machine Learning Track is mathematically rigorous. These guidelines help you assess your background and plan the right preparation to benefit fully from the program.
Linear algebra and multivariate calculus.
Solid understanding of probability theory.
Python experience helps, but the Python Primer is included.
Finance experience helps, but the Finance Primer is included.
Free self-paced primers help you refresh and strengthen your foundations before and during the program.
Refresh core math concepts.
Review key finance concepts.
Build Python skills for quantitative work.
Have questions about your background or preparation?
Talk to an AdvisorARPM was founded by Attilio Meucci and is built around decades of experience in quantitative investment, risk management and research.
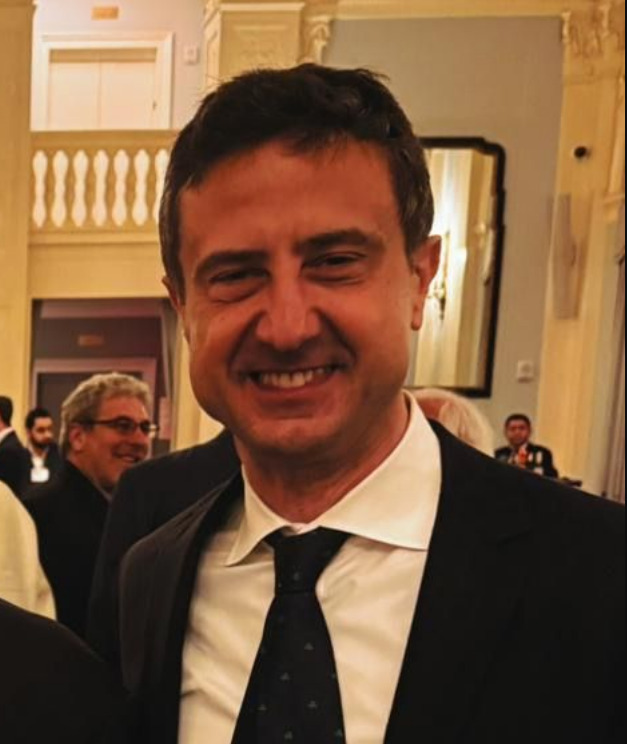
Attilio Meucci is the founder of ARPM, author of Risk and Asset Allocation, and a former senior quantitative investment and risk practitioner.




 (opens in a new tab)
Quantitative Research, Portfolio & Risk Management
“A vast wealth of material… quite unified across the program.”
(opens in a new tab)
VP · Risk & Quantitative Analytics
“The strong theoretical material, flexibility, Lab and live classroom sessions really stand out.”
(opens in a new tab)
Counterparty Credit Risk
“The two main advantages are the theory materials and the Python code.”
Watch more video reviews and read participant experiences.
See all reviews (opens in a new tab)The Machine Learning Track is a 5-month, part-time advanced learning program focused on the mathematical and probabilistic foundations of machine learning and their applications to financial data. It includes four courses: Mathematical Statistics for Finance, Mean-Covariance Learning, Probabilistic Machine Learning, and Time Series and Reinforcement Learning.
No. The Machine Learning Track is not a professional certification on its own. Participants who successfully complete the program receive an ARPM Statement of Completion documenting the courses completed.
The program does not teach machine learning as a collection of isolated algorithms. It develops a rigorous progression from statistical inference and estimation to mean-covariance methods, probabilistic machine learning, causality, time series, stochastic processes, and sequential decision-making, with applications throughout to financial data.
The Track is designed for quantitative professionals and advanced learners, including quant researchers, risk managers, asset managers, financial engineers, data scientists, developers, and graduate students with a strong mathematical background who want a deeper understanding of machine learning.
No. The Quant Bootcamp is a short, intensive introduction to key ARPM methodologies. The Machine Learning Track is a structured 5-month program that develops the subjects in substantially greater depth through four advanced courses, assignments, learning resources, and ongoing support.
You should be comfortable with linear algebra, multivariate calculus, and probability. The program is mathematically rigorous. ARPM Primers are available to review the required foundations if needed.
Python experience is helpful, but you do not need to be a professional software developer. Python is used to connect the mathematical concepts to numerical implementations and applied examples through the ARPM Lab.
No. Implementation is an important part of the program, but the main objective is to understand the models themselves: their assumptions, statistical foundations, estimation methods, limitations, and relationships with other learning approaches.
Topics include statistical inference and estimation, PCA and factor models, covariance estimation and regularization, regression, clustering, graphical models, classification, neural networks, causal models, random matrix theory, time-series models, Kalman filtering, GARCH, hidden Markov models, stochastic processes, and sequential decision-making.
Yes. The Track is designed as a part-time program for working professionals. Live sessions are recorded, and participants can combine the structured learning path with a full-time job while dedicating regular time each week to study and assignments.
The program runs for approximately 5 months and consists of four advanced courses studied as a structured learning sequence.
Participants have access to the ARPM learning platform and Lab, AI Tutor support, technical assistance, course resources, and human feedback on homework projects and assignments.
Contact us before enrolling. An ARPM advisor can help you assess whether your mathematical background, professional goals, and available study time are appropriate for the Machine Learning Track.